Contents
- What do UK companies benefit from ESG reporting?
- What are the ESG reporting requirements in the UK?
- ESG Reporting Process: Step-by-Step for UK Companies
- Key Challenges in ESG Reporting in the UK and How to Address Them
- How Can ESG Reporting Software Help
- Build a Future-Ready UK ESG Reporting System with Presgo
Talk to an ESG expert about how Presgo can help you.
Book a ConsultationAs environmental, social, and governance (ESG) reporting requirements in the UK expand, sustainability reporting is already well established among the country’s largest companies. The Financial Reporting Council found that the share of FTSE 350 companies obtaining sustainability assurance rose from 39% in 2019 to 57% in 2023. By 2025, 86 FTSE 100 companies had reported obtaining external assurance over their sustainability metrics, up from 74 in 2023.
Data accuracy remains a challenge, with 69% of FTSE 100 companies adjusting prior-year climate and sustainability figures in their latest annual reports. Rising assurance and frequent adjustments point to the same pressure: data that is accurate, traceable, and ready for scrutiny.
Driven by regulatory updates, global sustainability alignment, and climate efforts, the ESG reporting landscape in the UK is entering a new phase in 2027. This guide will provide an overview of the new UK ESG reporting requirements, identifying the companies required, relevant frameworks, and best practices to streamline ESG reporting.
What do UK companies benefit from ESG reporting?
ESG reporting refers to the structured disclosure of a company’s sustainability performance across the three pillars of environment, social, and governance. It involves collecting, analysing, and publishing data that reflects how a company manages its material impacts on people and the planet, as well as its internal governance structures.
For UK companies operating in global financial markets, ESG reporting should be considered a strategic necessity and not just a compliance exercise. Investors are now including ESG performance in their investment decisions, consumers are demanding transparency on sustainable business practices, and regulators are increasingly including ESG reporting requirements in their guidelines. Companies that fail to meet ESG expectations risk reputational damage, losing access to new sources of capital, and falling behind competitors who have already incorporated sustainability and ESG reporting into their business strategies.
What are the ESG reporting requirements in the UK?
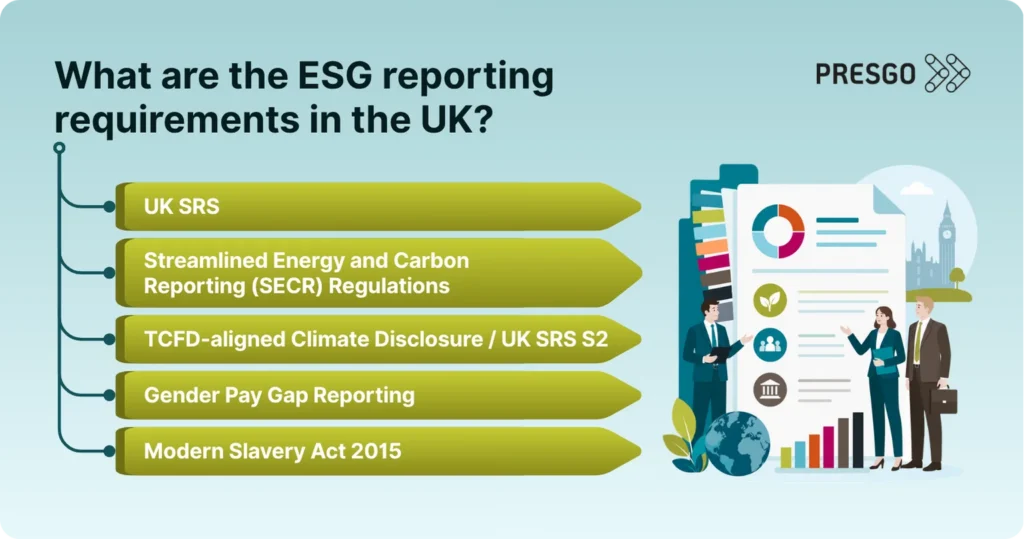
In the UK, ESG reporting requirements are shaped by a combination of global, regional, and national frameworks that aim to standardise ESG disclosures and improve transparency for investors and stakeholders. As sustainability becomes a strategic priority, UK companies must navigate both international expectations and domestic mandates.
Globally, companies widely use international ESG reporting frameworks such as the GRI Universal Standards and the SASB Industry-Specific Standards. These are voluntary initiatives that are widely used internationally, facilitating the disclosure of comparable ESG performance data across the board.
In the European region, the Corporate Sustainability Reporting Directive (CSRD) significantly expands ESG reporting requirements with the European Sustainability Reporting Standards (ESRS). Under the EU’s Omnibus I simplification package, the CSRD now applies to EU companies with more than 1,000 employees and more than €450 million in net annual turnover. UK groups with substantial EU operations are still in scope, and non-EU companies are covered if they generate more than €450 million in net turnover for two consecutive financial years and have an EU subsidiary or branch with more than €200 million in net turnover. In-scope companies report using the ESRS, which mandates double materiality assessments, value chain disclosures, and third-party assurance.
To align with international best practices, the UK has developed its own Sustainability Reporting Standards (UK SRS). These are based on IFRS S1 and S2 standards that were published by the International Sustainability Standards Board (ISSB) in 2023. On 25 February 2026, the Department for Business and Trade published the final UK SRS S1 and S2, which are now available for voluntary use. The standards reflect UK-specific policy priorities while keeping divergence from IFRS S1 and S2 to a minimum.
UK SRS adoption is moving forward through two routes. For listed companies, the Financial Conduct Authority (FCA) has finalised rules replacing its Task Force on Climate-Related Financial Disclosures (TCFD)-aligned listing rules with UK SRS-aligned requirements, published in Policy Statement PS26/19 on 30 September 2026. In-scope companies are required to report against UK SRS S1 and S2 on a “comply or explain” basis for accounting periods beginning on or after 1 January 2027, with transitional reliefs of one year for scope 3 emissions disclosures and two years for wider sustainability disclosures under UK SRS 1.
In its consultation, the FCA estimated that around 600 listed companies would be affected, including 515 in the commercial companies, non-equity shares, and non-voting equity shares, and transition categories. The final rules also extend to the remaining 89 issuers with secondary listings or depositary receipts. For other companies, including private companies, the government has said it will consult on mandatory reporting through its Modernising Corporate Reporting programme.
Other ESG reporting requirements in the UK include:
- Streamlined Energy and Carbon Reporting (SECR) Regulations: Requires UK-incorporated companies, large unquoted companies incorporated in the UK, and large LLPs to report on their company’s energy use, greenhouse gas emissions, and energy efficiency actions. The government is reviewing how SECR interacts with UK SRS to reduce duplication.
- TCFD-aligned Climate Disclosure / UK SRS S2: Two requirements currently apply. The Climate-related Financial Disclosure Regulations 2022 mandate climate-related disclosures aligned with the TCFD recommendations for large companies and LLPs. Separately, the Financial Conduct Authority (FCA) Listing Rule requires companies in the commercial companies listing category to make disclosures against the TCFD recommendations and recommended disclosures on a “comply or explain” basis. The TCFD was disbanded in 2023, and UK SRS S2 now builds on its recommendations. The government has confirmed that public companies reporting in line with UK SRS S2 meet the Companies Act requirements, and the FCA has finalised rules replacing its TCFD-aligned requirement with UK SRS-aligned ones, applying to accounting periods beginning on or after 1 January 2027.
- Gender Pay Gap Reporting: Employers in the UK with over 250 employees are required to publish their gender pay gap data annually. Since April 2026, large employers can also publish voluntary equality action plans, which are expected to become mandatory from spring 2027.
- Modern Slavery Act 2015: Requires companies operating in the UK to publish an annual modern slavery statement that includes the steps taken to address modern slavery risks in their operations and supply chains. Proposed amendments introduced in June 2026 would make statements more prescriptive and introduce financial penalties for non-compliance, if enacted.
Together, these frameworks and regulations form a comprehensive ESG reporting landscape that UK companies must navigate. The shift towards the new UK SRS that’s aligned with the ISSB’s IFRS S1 and S2 standards signals a move toward greater consistency and comparability in ESG reporting requirements.
ESG Reporting Process: Step-by-Step for UK Companies
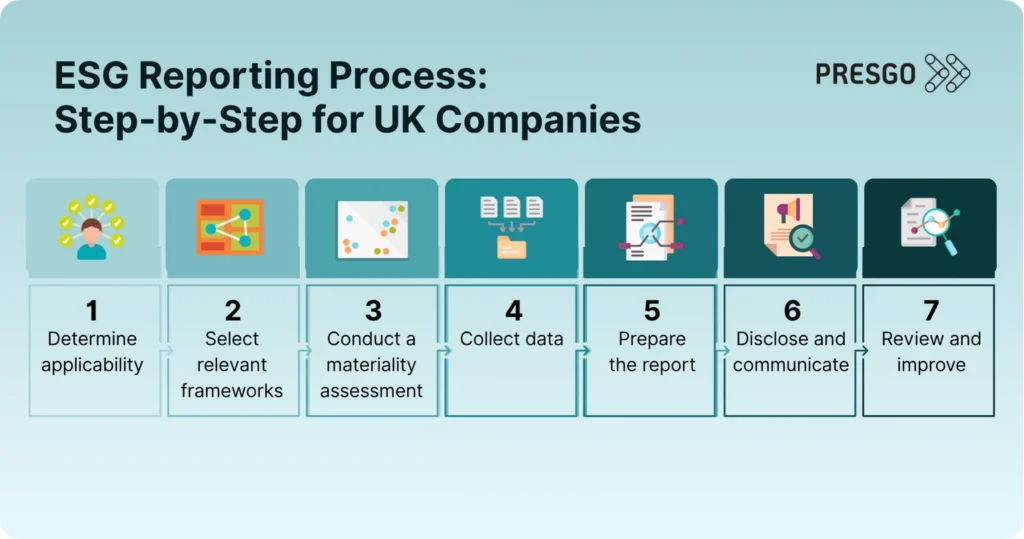
Navigating ESG reporting can be complex, but a structured approach can ease the process. Here’s a quick step-by-step guide for UK companies to follow:
- Determine applicability: Assess whether your company is subject to any mandatory ESG reporting regulations and whether there are any requirement thresholds based on size, sector, or listing status.
- Select relevant frameworks: Choose the appropriate ESG reporting standards (e.g., GRI, TCFD, UK SRS S1 and S2, IFRS S1 and S2) based on regulatory requirements and usability.
- Conduct a materiality assessment: Identify which ESG topics are most relevant to your specific business context, based on actual and potential impacts and stakeholder input.
- Collect data: Gather quantitative and qualitative data across the business, covering all significant locations and operations. Ensure that your data is accurate and consistent. Use internal audits or third-party verification to validate your data where necessary.
- Prepare the report: Write and structure the report according to the chosen standard(s) and/or frameworks, focusing on your identified material ESG topics.
- Disclose and communicate: Publish your report through annual filings, sustainability reports, or digital platforms.
- Review and improve: Use insights from the reporting process to enhance ESG strategies and prepare for future disclosures.
Key Challenges in ESG Reporting in the UK and How to Address Them
UK companies face four recurring obstacles in meeting ESG reporting requirements. Each can be managed with clear ownership and well-defined processes. The sections below outline what each challenge involves and the practical actions that address it.
Fragmented ESG Data Collection
Data collection is often fragmented across departments, making it difficult to ensure consistency and accuracy. Without integrated systems and processes, companies may struggle to consolidate and validate ESG metrics effectively.
Recommended actions:
- Map ESG data sources and assign a named data owner in each department.
- Standardise metric definitions, units, and calculation methods across the business.
- Centralise data collection in a single system to replace scattered spreadsheets and email threads.
- Build validation checks and audit trails into the collection workflow.
Managing Multiple ESG Reporting Frameworks
The regulatory landscape is complex and constantly evolving. For companies operating internationally, there may be a need to align with both local and international standards, resulting in added complexity. These companies must be able to navigate multiple frameworks simultaneously, each with its own set of requirements and guidelines.
Recommended actions:
- Confirm which regimes apply, and recheck thresholds regularly as scopes change.
- Map overlapping disclosure requirements across frameworks, using the close alignment between UK SRS and IFRS S1 and S2 as a baseline.
- Collect data once and reuse it across reports instead of running separate exercises per framework.
- Prioritise mandatory requirements first, then voluntary frameworks.
Limited Expertise and Assurance Readiness
Many organisations lack the internal expertise and resources to manage ESG reporting effectively. Smaller companies may not have dedicated sustainability teams, while larger ones often face coordination issues across departments and locations. As ESG disclosures increasingly require external assurance, companies must also prepare for audit-level scrutiny, which demands robust internal controls and documentation.
Recommended actions:
- Identify skill gaps and train finance and sustainability teams on UK SRS and its links to financial reporting.
- Define clear roles and responsibilities across finance, sustainability and operations.
- Document methodologies, assumptions, and supporting evidence for every reported metric.
- Run a readiness review ahead of external assurance, noting that ISSA (UK) 5000 applies to assurance engagements for periods beginning on or after 15 December 2026.
Keeping Pace with Regulatory Change
The pace of regulatory changes regarding ESG reporting requirements can result in uncertainty. New requirements require companies to stay agile and continuously adapt their reporting strategies and processes, which can put a strain on already limited resources.
Recommended actions:
- Assign an owner to track developments from the FCA, the Department for Business and Trade, and the EU.
- Keep a regulatory tracker that records each requirement’s status and key dates.
- Assess the gap between current TCFD-aligned disclosures and UK SRS requirements.
- Design reporting processes and data structures that can adapt to new requirements without a rebuild.
How Can ESG Reporting Software Help
ESG reporting software can help companies overcome these key challenges by centralising and automating data collection across departments, ensuring consistency and accuracy. These platforms support multiple frameworks, easing the burden of navigating evolving regulations. They also enhance audit readiness through features like traceable data audit trails and built-in validation tools.
For organisations with limited ESG expertise, the software simplifies compliance by providing guided workflows and templates. Additionally, real-time dashboards and analytics support better decision-making and continuous improvement in sustainability performance.
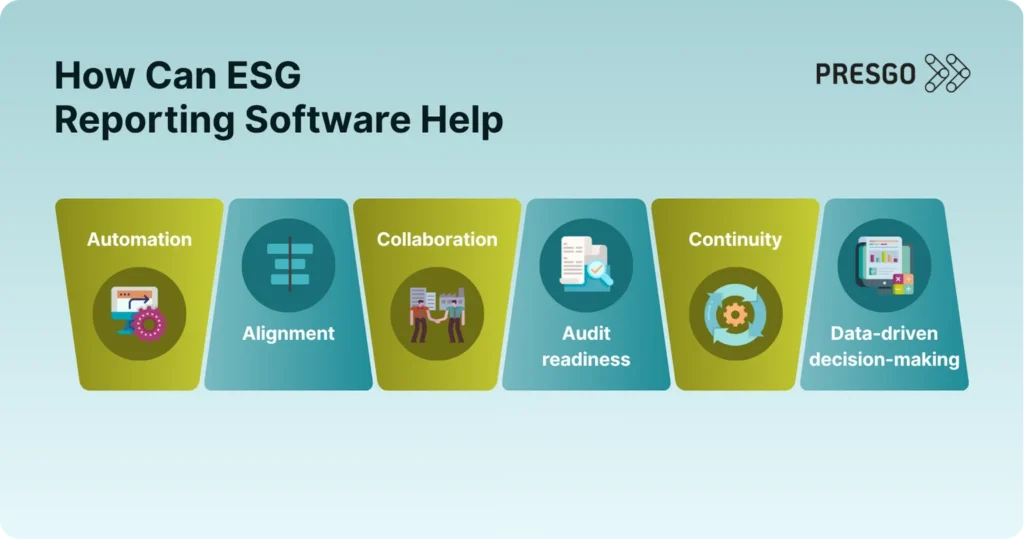
Making use of an ESG reporting platform helps companies reduce the burden of manual reporting and improve the quality of ESG disclosures. In short, modern ESG reporting solutions offer the following advantages:
- Automation: Streamline data collection and report writing processes.
- Alignment: Ensure compliance with multiple ESG reporting standards simultaneously.
- Collaboration: Data owners can submit and review data as needed.
- Audit readiness: Ensure collected ESG data is traceable and evidence-based.
- Continuity: Retain historic data in one place, so year-on-year comparisons remain consistent as standards, methodologies, and reporting scopes change.
- Data-driven decision-making: Simplified data presentation facilitates strategic decision-making.
Build a Future-Ready UK ESG Reporting System with Presgo
As UK reporting requirements move towards the UK SRS, technology is becoming central to how companies keep pace. Purpose-built reporting tools replace scattered spreadsheets with a single, controlled process for collecting, validating, and publishing ESG data. This cuts manual effort and the risk of error, and gives finance and sustainability teams a shared view of the same numbers. It also builds the evidence trail that external assurance depends on. The result is less time spent on compliance mechanics and more time acting on what the data shows.
Presgo is a purpose-built platform that helps companies centralise their ESG data, align disclosures across multiple frameworks, and maintain consistency as regulations evolve. For UK organisations navigating the transition to more rigorous ESG reporting, Presgo offers a practical, scalable solution.
Designed to support UK ESG reporting needs, Presgo aligns with IFRS S1 and S2, UK SRS, GRI, TCFD, and other global standards. It streamlines data collection across teams and operations, improves audit readiness through traceable and verifiable data, and supports year-on-year comparability. By reducing manual effort and increasing data reliability, Presgo enables companies to focus beyond compliance. It facilitates data-driven decision-making for future-ready sustainability practices and disclosures.
With 2026 marking a pivotal year for ESG reporting requirements in the UK, companies that act now to strengthen their ESG will be better positioned to meet evolving ESG developments.
Get future-ready with us at Presgo. Book a demo today.